Contact us
Send Us Your Case Details
We’ll respond and let you know the best way to proceed with your case.

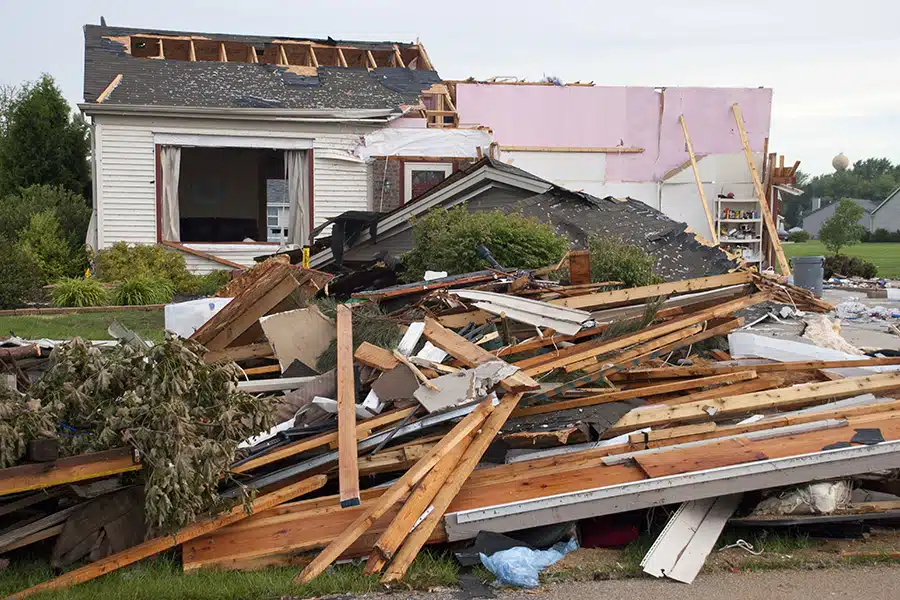
When disaster strikes, the last thing you want is to discover that your insurance policy doesn’t cover what you thought it did. Yet, many people find themselves in this exact situation, facing significant financial hardship at a time when they can least afford it. Insurance policies, especially those dealing with disasters, can be complicated documents filled with legal jargon that is difficult to navigate. It’s not uncommon for important details to be buried within the fine print, leaving policyholders unaware of critical coverage limitations.
At Strickland Law Group, we understand the challenges and frustrations that come with dealing with insurance companies, particularly in the aftermath of a disaster. Our expertise lies in helping individuals understand the intricacies of their insurance policies, ensuring they receive the coverage they’re entitled to, and fighting on their behalf when disputes arise. This blog post aims to shed light on some of the hidden aspects of disaster insurance policies that can affect your coverage. Whether you’re a homeowner, a renter, or a business owner, knowing these details is crucial to protecting your assets and securing your financial future.
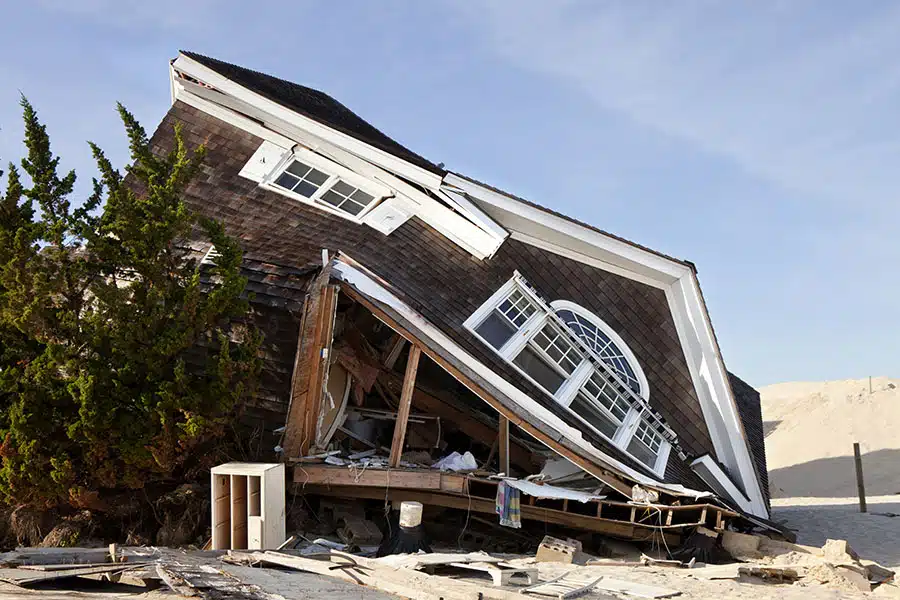
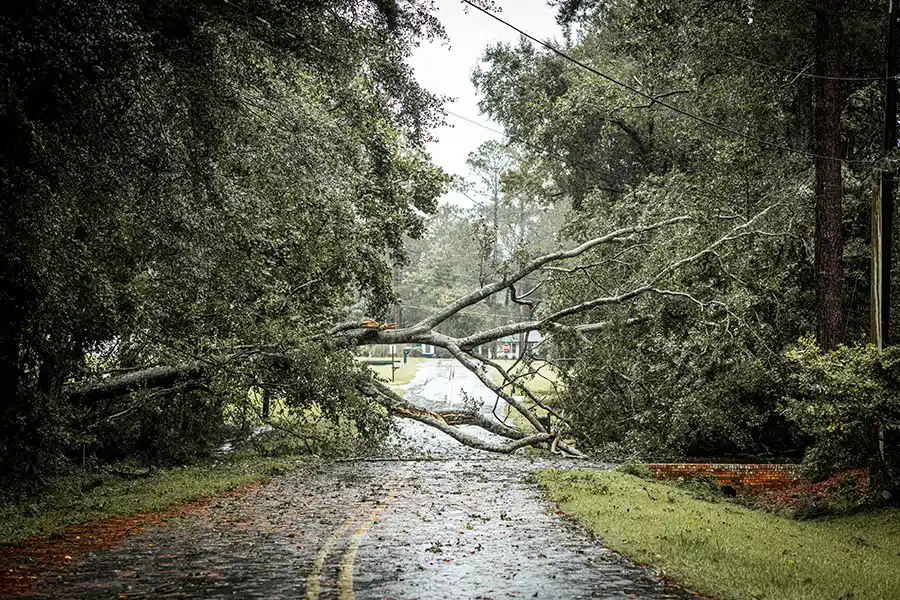
Disaster insurance policies are designed to protect you in the wake of natural and man-made catastrophes, from hurricanes and floods to fires and earthquakes. Yet, the protection they offer is not as straightforward as one might hope. The complexity of these policies often lies in their detailed exclusions, limits, and conditions—elements that are not always clear to the policyholders.
One of the first hurdles in understanding your disaster insurance policy is navigating the dense legal language it contains. Terms like “deductible,” “actual cash value,” “replacement cost,” and “exclusions” can have specific meanings that significantly impact your coverage. For instance, the difference between the actual cash value and replacement cost can affect the amount you’re reimbursed after a loss, potentially leaving you out of pocket.
It’s not uncommon for important coverage details to be buried in the fine print of your policy. These details may include:
A common misunderstanding about disaster insurance is the belief that one policy covers all types of disasters. In reality, you may need multiple policies to be fully protected against a range of events. Another misconception is assuming that insurance will cover the full cost of rebuilding or repairs, which is not always the case, especially if you’re underinsured.
The implications of not fully understanding your disaster insurance policy can be severe. In the aftermath of a disaster, you may find yourself facing unexpected coverage gaps, leading to significant financial strain. For example, discovering that your policy doesn’t cover flood damage after a hurricane can be devastating.
At Strickland Law Group, we’ve seen firsthand the challenges and frustrations that come from these misunderstandings and oversights. That’s why we emphasize the importance of thoroughly reviewing and understanding your insurance policies before disaster strikes. Knowing exactly what your policy covers, what it excludes, and how to navigate its complexities can make a substantial difference in your ability to recover from a disaster.
Disaster insurance policies are filled with clauses that, while seemingly innocuous, can have profound implications on your coverage. Understanding these hidden clauses is essential to grasping the full scope of your protection. Below, we delve into some of these clauses and what they mean for you as a policyholder.
A particularly tricky aspect of some insurance policies is the “anti-concurrent causation” clause. This clause can deny coverage for losses caused by a combination of covered and excluded perils. For example, if a hurricane causes both wind damage (covered) and flood damage (excluded), this clause might prevent you from claiming the wind damage because the events occurred concurrently. Understanding the presence and implications of this clause in your policy is crucial, as it can significantly impact your ability to claim after a disaster.
Another important clause to be aware of is related to the depreciation of property value, often referred to as “wear and tear” exclusions. Insurance companies might reduce the payout for damaged property by considering its depreciated value rather than the cost to replace it. This can leave you with a gap between the insurance payout and the actual cost to repair or replace your property, affecting your financial recovery after a disaster.
Mandatory arbitration clauses are increasingly common in insurance policies. These clauses require policyholders to resolve disputes through arbitration rather than through the court system. While arbitration can be faster and less expensive than going to court, it also means giving up the right to sue the insurance company or participate in a class-action lawsuit. Policyholders should be aware of this clause, as it limits legal recourse in the event of a dispute.
The presence of these and other hidden clauses in disaster insurance policies can catch many policyholders off guard, leading to unexpected denials of coverage or reduced payouts. It’s not just about the financial implications; it’s also about the emotional and psychological impact of feeling unprotected when you need it most.
This is where legal expertise comes into play. At Strickland Law Group, we specialize in dissecting these complex policies, identifying potential pitfalls, and advising our clients on the best course of action. Whether it’s negotiating with insurance companies or challenging unfair policy interpretations, our goal is to ensure that you are fully informed and adequately protected.
A well-structured disaster insurance policy is your first line of defense against the financial devastation that can follow natural and man-made disasters. However, even the most diligent policyholders can find themselves facing unexpected coverage gaps. These gaps can leave you vulnerable, turning what should be a manageable recovery process into a financial nightmare.
Being underinsured is another critical gap that can have long-term financial consequences. If the coverage limits of your policy are too low to cover the cost of rebuilding or replacing your property, you will bear the brunt of the shortfall. This situation is especially common when property values have increased, or when improvements have been made without adjusting the insurance coverage accordingly.
Understanding your risk exposure and the specifics of your insurance coverage is the first step in mitigating these risks. Regularly reviewing your policy, ideally with the help of legal or insurance professionals, can help identify and bridge these gaps before they become a problem. Here are a few steps to consider:
At Strickland Law Group, we’ve dedicated ourselves to helping our clients navigate the complex landscape of disaster insurance. Our team is skilled in identifying potential coverage gaps and advocating for policy adjustments that offer comprehensive protection. We believe in empowering our clients with knowledge and support, ensuring that when disaster strikes, you’re ready and resilient.
Facing a dispute with your insurance company can be daunting, especially in the aftermath of a disaster when you’re most in need of support. At Strickland Law Group, we specialize in representing policyholders who find themselves at odds with their insurance providers, ensuring that your rights are protected and your voice is heard. Our approach to insurance disputes includes:
When you’re facing a dispute with your insurance company, you don’t have to go it alone. Strickland Law Group are here to stand up for your rights, offering the expert legal representation you need to navigate the complexities of insurance disputes. With us by your side, you can have confidence in your pursuit of fair compensation.